Important Update – Supreme Court Position as of August 2026
The legal position concerning Input Tax Credit (ITC) where a supplier fails to deposit GST has undergone an important development since this article was originally published in February 2026.
During 2025 and early 2026, several High Court decisions examined whether a bona-fide purchaser should lose ITC merely because the supplier failed to deposit the tax collected from the buyer. Some of these decisions provided relief to genuine purchasers and emphasised factors such as the genuineness of the transaction, payment through banking channels and absence of fraud or collusion.
One important decision was Sahil Enterprises v. Union of India, where the Tripura High Court granted relief to a bona-fide purchaser and read down Section 16(2)(c) of the CGST Act in the circumstances before it.
However, the judicial position subsequently developed further.
In Bhandari Scrap Traders v. Union of India & Ors., by order dated 24 July 2026, the Supreme Court affirmed the Gujarat High Court’s approach that Section 16(2)(c) is constitutionally valid and is not required to be read down merely to protect a bona-fide purchaser.
Accordingly, the earlier High Court decisions discussed in this article should now be understood as part of the evolution of judicial interpretation of Section 16(2)(c) rather than as establishing an absolute rule that ITC can never be denied to a genuine purchaser because of supplier default.
This article therefore examines how the judicial approach developed across different High Courts and how the subsequent Supreme Court decision affects the legal position in 2026.
Brief Legislative Background (Why this problem even started)
When GST came in, the idea was simple:
- Buyer gets Input Tax Credit (ITC)
- Supplier pays tax to the Government
- Everyone stays compliant
But then came Section 16(2)(c) of the CGST Act, which says:
ITC is allowed only if tax charged has actually been paid to the Government by the supplier.
On paper, this looks logical.
In reality? Buyers were punished for mistakes they never committed.
Overview of Statutory Provisions Interpreted
The courts mainly examine
Section 16(2)(c), CGST Act
- Makes buyer’s ITC dependent on supplier’s tax payment
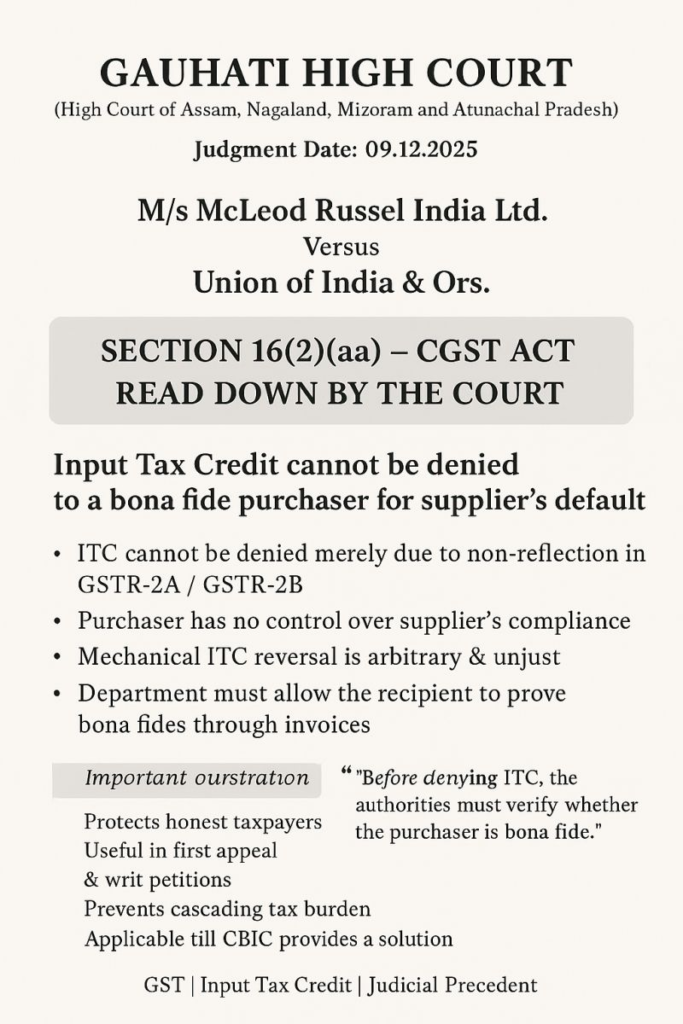
Section 16(2)(aa)
- Invoice must be reflected in GSTR-2B
Principles of Natural Justice
- You cannot penalize someone without fault
- Law should be reasonable, not oppressive
Detailed Analysis of the Judgments (What Courts Actually Said)
Tripura High Court – Sahil Enterprises v. Union of India
The Sahil Enterprises judgment represented an important taxpayer-friendly interpretation of Section 16(2)(c) at the High Court level.
The Tripura High Court considered the practical difficulty faced by a genuine purchaser who had paid GST to the supplier but had no effective control over whether the supplier subsequently deposited that tax with the Government.
The Court noted, among other factors, that:
- the purchaser had entered into a genuine transaction;
- GST had been paid to the supplier;
- the purchaser could not control the supplier’s subsequent tax compliance; and
- the statutory machinery was available to the Government for proceeding against a defaulting supplier.
The Court did not strike down Section 16(2)(c) as unconstitutional. Instead, it upheld the provision while reading it down in the circumstances before it so that ITC was not denied to the bona-fide purchaser merely because of the supplier’s failure to deposit GST.
Result: Relief was granted to the purchaser and the disputed ITC was restored.
Subsequent development: The approach adopted in Sahil Enterprises must now be read in light of the Supreme Court’s July 2026 decision in Bhandari Scrap Traders, discussed later in this article.
🏛 Kerala High Court – Santhom Metacast (P.) Ltd.
Kerala HC echoed the same logic:
- Buyer fulfilled all conditions
- Payments made through banking channels
- No allegation of fraud or collusion
👉 ITC denial was held unsustainable.
🏛 Calcutta High Court – Anjita Dokania
This case strengthened the taxpayer’s position:
- Authorities must first act against defaulting supplier
- Buyer should not be the “easy target”
Evolution of the Judicial Approach
The judicial approach to Section 16(2)(c) has evolved considerably.
Earlier Taxpayer-Friendly Approach
Several High Court decisions examined the hardship faced by genuine purchasers where GST had been paid to the supplier but was not subsequently deposited with the Government.
Depending upon the facts of individual cases, courts considered factors such as:
- genuineness of the underlying transaction;
- actual receipt of goods or services;
- payment to the supplier through banking channels;
- availability of proper tax invoices;
- absence of fraud or collusion; and
- whether the Department had taken appropriate action against the defaulting supplier.
These decisions contributed to an important judicial debate over whether a bona-fide purchaser should automatically lose ITC because of a default committed by the supplier.
Supreme Court Development – Bhandari Scrap Traders
The legal position assumed greater significance after the Supreme Court’s decision in Bhandari Scrap Traders v. Union of India & Ors. dated 24 July 2026.
The Supreme Court agreed with the approach taken by the Gujarat High Court regarding Section 16(2)(c) and upheld the validity of the statutory condition requiring the tax charged in respect of the supply to have actually been paid to the Government.
The Court did not accept that Section 16(2)(c) was required to be read down merely because compliance with the supplier’s tax-payment obligation may be difficult for the purchasing dealer to verify.
Accordingly, bona-fide conduct by the purchaser remains an important factual consideration, particularly in disputes involving allegations of fraud, fake invoices or collusion. However, bona-fide conduct by itself should not be treated as creating an automatic statutory entitlement to ITC where the conditions prescribed under Section 16 are not satisfied.
Position After the Supreme Court Decision
The earlier High Court judgments remain relevant for understanding the development of GST jurisprudence and the factual protection considered appropriate in genuine transactions.
However, after the Supreme Court’s July 2026 decision, businesses should not proceed on the assumption that payment of GST to the supplier, possession of an invoice or absence of collusion will automatically protect ITC where the statutory requirements are otherwise not fulfilled.
The practical lesson is therefore clear: buyer diligence remains important, but compliance with the statutory conditions governing ITC remains fundamental.
Practical Implications for Businesses
The Supreme Court development makes vendor compliance and documentation even more important for businesses claiming Input Tax Credit.
Businesses should consider the following safeguards:
- verify the GST registration and compliance profile of important suppliers;
- ensure that invoices and supplies are genuine and properly documented;
- reconcile purchase records regularly with GSTR-2B;
- make payments through traceable banking channels;
- maintain purchase orders, invoices, e-way bills, goods-receipt records and payment evidence, wherever applicable;
- identify repeated vendor compliance failures at an early stage; and
- respond promptly and with complete documentation if an ITC discrepancy or notice arises.
A genuine transaction and proper documentation remain extremely important in defending an ITC dispute. However, after the Supreme Court’s July 2026 decision, businesses should not assume that bona-fide conduct alone overrides the statutory conditions prescribed for availing ITC.
Key Takeaways from the Judicial Evolution
The judicial journey on supplier-default ITC provides several important lessons:
- High Courts highlighted genuine buyer hardship: Several decisions examined whether an innocent purchaser should bear the consequences of a supplier’s failure to deposit GST.
- Sahil Enterprises provided significant buyer relief: The Tripura High Court read down Section 16(2)(c) in the circumstances before it and restored ITC to the bona-fide purchaser.
- The Supreme Court subsequently reinforced the statutory condition: In Bhandari Scrap Traders, the Supreme Court upheld the validity and operation of Section 16(2)(c) and did not accept that the provision must be read down merely because the purchaser may find supplier compliance difficult to verify.
- Bona-fide conduct is not an automatic guarantee of ITC: Genuine transactions, proper invoices and absence of collusion remain relevant facts, but the statutory conditions governing ITC continue to be important.
- Prevention is increasingly important: Vendor due diligence, GSTR-2B reconciliation and strong documentation should form part of a business’s regular GST compliance controls.
Conclusion
The controversy surrounding ITC denial due to supplier default illustrates the continuing tension between protecting government revenue and addressing the practical difficulties faced by genuine purchasers.
Earlier High Court decisions played an important role in highlighting the hardship that may arise where a purchaser has paid GST to the supplier but the supplier subsequently defaults in depositing the tax.
However, the Supreme Court’s decision in Bhandari Scrap Traders has materially influenced the legal position by affirming the statutory importance of Section 16(2)(c).
Businesses should therefore avoid treating earlier taxpayer-friendly High Court decisions as providing an unconditional shield against ITC denial. The safer approach is to combine careful vendor selection, regular reconciliation, strong documentary evidence and timely action whenever supplier non-compliance is detected.
For businesses facing an actual supplier-default situation, the practical question may extend beyond defending the ITC claim to examining contractual safeguards and possible recovery from the defaulting supplier.
Related Guide: If you are dealing with an actual supplier-default case, read our detailed guide, ITC Denied Due to Supplier Default: Can the Buyer Recover the Loss? which explains practical safeguards, recovery options and contractual protection for buyers.
Frequently Asked Questions (FAQs)
FAQ 1: Can GST ITC be denied if the supplier fails to pay tax to the Government?
Section 16(2)(c) of the CGST Act makes payment of the tax charged on the supply to the Government one of the statutory conditions governing ITC.
Although several High Courts had granted relief to bona-fide purchasers in particular factual circumstances, the Supreme Court’s July 2026 decision in Bhandari Scrap Traders upheld the validity and operation of Section 16(2)(c).
Therefore, payment of GST by the purchaser to the supplier does not, by itself, guarantee entitlement to ITC if the statutory conditions are not satisfied.
FAQ 2: Does being a bona-fide buyer automatically protect GST ITC?
No. Bona-fide conduct remains important, particularly when determining whether the transaction is genuine and whether there is any fraud, collusion or fake invoicing.
However, after the Supreme Court’s decision in Bhandari Scrap Traders, bona-fide conduct alone should not be treated as overriding the statutory conditions prescribed for claiming ITC.
FAQ 3: What did the High Courts say about supplier-default ITC?
Several High Courts examined the hardship faced by genuine purchasers where GST had been paid to the supplier but the supplier failed to deposit the tax with the Government.
Depending upon the facts of the individual cases, some courts granted relief by considering factors such as genuine receipt of goods or services, payment through banking channels, proper documentation and absence of fraud or collusion.
These decisions remain important in understanding the evolution of GST jurisprudence, but they must now be read in light of the subsequent Supreme Court development.
FAQ 4: What is the significance of the Supreme Court’s Bhandari Scrap Traders decision?
The Supreme Court agreed with the Gujarat High Court’s approach and upheld the validity of Section 16(2)(c). It did not accept that the provision was required to be read down merely because a purchasing dealer may find it difficult to verify whether the supplier has actually deposited GST with the Government.
The decision therefore reinforces the importance of satisfying the statutory conditions governing ITC.
FAQ 5: How can businesses reduce the risk of ITC disputes caused by supplier default?
Businesses should strengthen their vendor-compliance controls by:
- conducting appropriate vendor due diligence;
- checking GST registration and compliance status;
- regularly reconciling purchase records with GSTR-2B;
- maintaining invoices, purchase orders, e-way bills and goods-receipt records, wherever applicable;
- making payments through traceable banking channels;
- monitoring repeated supplier defaults; and
- responding promptly to ITC discrepancies and GST notices.
These precautions cannot independently override the statutory requirements for ITC, but they can strengthen compliance, documentation and the factual defence available in the event of a dispute.
Disclaimer
This publication is intended solely for informational and educational purposes and does not constitute professional, legal, tax, or financial advice. The information provided has been compiled from sources believed to be reliable; however, its accuracy, completeness, or current relevance is not guaranteed. The views and opinions expressed herein reflect the author’s understanding at the time of publication and are subject to change without notice.
Readers are strongly advised to seek independent professional advice before making any decision or taking any action based on the information contained in this publication. The author and publisher expressly disclaim any responsibility or liability for any loss, damage, or consequence arising directly or indirectly from reliance on this content or from any action taken or not taken based on it.